2026 child tax credit at a glance
| Item | 2026 |
|---|---|
| Maximum credit per qualifying child (under 17) | $2,200 |
| Refundable portion (additional child tax credit) | Up to $1,700 per child |
| Refundability formula | 15% of earned income above $2,500 |
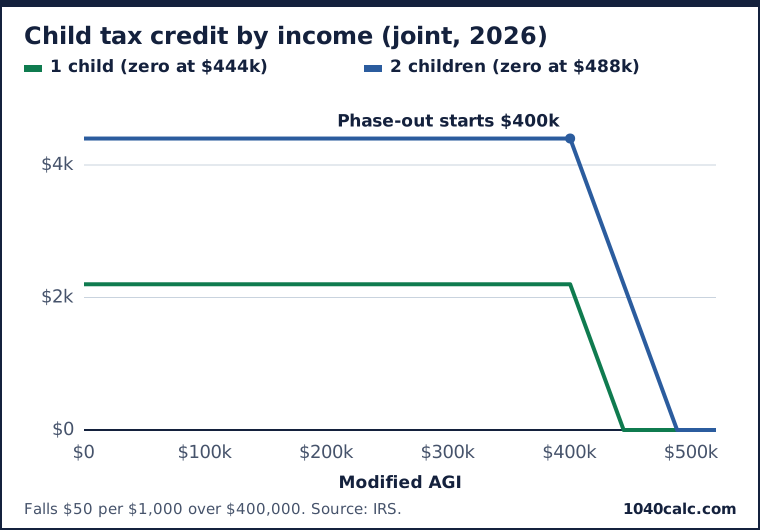
| Phase-out begins (modified AGI) | $200,000 · $400,000 married filing jointly |
| Reduction | $50 for each $1,000 (or part) above the threshold |
| Credit for other dependents (17+, parents, etc.) | $500, not refundable |
The One Big Beautiful Bill Act made the higher credit permanent at $2,200 starting in 2025 and indexed it for inflation; for 2026 the IRS kept it at $2,200 with a refundable limit of $1,700.
Who counts as a qualifying child
- Under age 17 at the end of 2026.
- Your son, daughter, stepchild, foster child, sibling, or a descendant of one of them.
- Lived with you more than half the year and didn’t provide more than half of their own support.
- Claimed as your dependent and a U.S. citizen, national or resident alien.
- Has a valid Social Security number issued before the return due date. Under the 2025 law, the taxpayer (or at least one spouse on a joint return) must also have a valid SSN.
How the refundable part works
The $2,200 first reduces any income tax you owe. If the credit is bigger than your tax, up to $1,700 per child can be refunded — but only up to 15% of your earned income above $2,500.
Single parent, two children, $28,000 of wages. After the $24,150 head-of-household standard deduction, taxable income is $3,850 and tax is $385. The credit wipes out the $385. Of the remaining $4,015, the refundable amount is the smallest of $4,015, 2 × $1,700 = $3,400, and 15% × ($28,000 − $2,500) = $3,825 → $3,400 refund from the credit.
Married couple, one child, $430,000. $30,000 over the $400,000 threshold → 30 × $50 = $1,500 reduction. Credit: $2,200 − $1,500 = $700.
Married couple, three children, $120,000. Below the phase-out, so the full 3 × $2,200 = $6,600 applies against their income tax.
Getting it in your paycheck instead
Enter $2,200 per child in Step 3 of Form W‑4 so your employer withholds less during the year. The W-4 calculator checks whether your withholding is on target, and the tax refund calculator shows how the credit affects your 2027 refund.