How the RMD is calculated
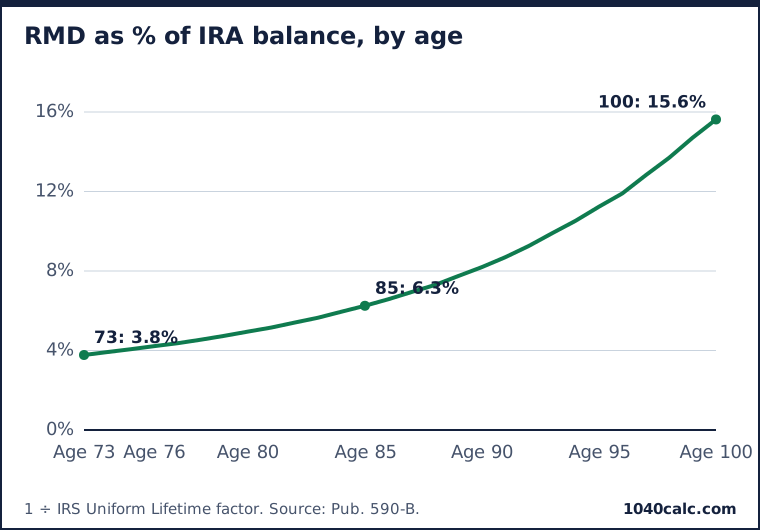
RMD = account balance on December 31 of the prior year ÷ distribution factor for your age. The factor comes from the IRS Uniform Lifetime Table, which most account owners use. For 2026 you use the December 31, 2025 balance and your age on your 2026 birthday.
Example. You turn 74 in 2026 and your IRA was worth $500,000 on December 31, 2025. The factor for age 74 is 25.5, so your 2026 RMD is $500,000 ÷ 25.5 = $19,608.
When RMDs start
| Born | RMD starting age | First RMD year |
|---|---|---|
| 1950 or earlier | Already started (70½ or 72 under old rules) | — |
| 1951 – 1959 | 73 | The year you turn 73 |
| 1960 or later | 75 (SECURE 2.0 Act) | The year you turn 75 |
The first RMD may be delayed until April 1 of the following year; every later RMD is due by December 31. If you delay the first one, you’ll take two in the same year — which can push you into a higher tax bracket or a Medicare IRMAA tier.
IRS Uniform Lifetime Table
Used by unmarried owners, married owners whose spouse isn’t more than 10 years younger, and married owners whose spouse isn’t the sole beneficiary.
| Age | Factor | Age | Factor |
|---|---|---|---|
| 72 | 27.4 | 97 | 7.8 |
| 73 | 26.5 | 98 | 7.3 |
| 74 | 25.5 | 99 | 6.8 |
| 75 | 24.6 | 100 | 6.4 |
| 76 | 23.7 | 101 | 6.0 |
| 77 | 22.9 | 102 | 5.6 |
| 78 | 22.0 | 103 | 5.2 |
| 79 | 21.1 | 104 | 4.9 |
| 80 | 20.2 | 105 | 4.6 |
| 81 | 19.4 | 106 | 4.3 |
| 82 | 18.5 | 107 | 4.1 |
| 83 | 17.7 | 108 | 3.9 |
| 84 | 16.8 | 109 | 3.7 |
| 85 | 16.0 | 110 | 3.5 |
| 86 | 15.2 | 111 | 3.4 |
| 87 | 14.4 | 112 | 3.3 |
| 88 | 13.7 | 113 | 3.1 |
| 89 | 12.9 | 114 | 3.0 |
| 90 | 12.2 | 115 | 2.9 |
| 91 | 11.5 | 116 | 2.8 |
| 92 | 10.8 | 117 | 2.7 |
| 93 | 10.1 | 118 | 2.5 |
| 94 | 9.5 | 119 | 2.3 |
| 95 | 8.9 | 120+ | 2.0 |
| 96 | 8.4 |
Rules worth knowing
- Each account type is figured separately. IRA RMDs can be added together and taken from any one IRA; 401(k) RMDs must be taken from each 401(k).
- Roth IRAs have no RMDs for the original owner, and since 2024 neither do Roth 401(k)s.
- Still working? You can usually delay RMDs from your current employer’s plan until you retire, unless you own more than 5% of the company. IRAs don’t get this exception.
- Qualified charitable distributions from an IRA (age 70½+) count toward your RMD but aren’t taxable income.
- Penalty: 25% of the amount you should have withdrawn, reduced to 10% if corrected within two years.